Washington keeps selling the same deal: tax “the rich” and corporations harder, and groceries, rent, and paychecks will somehow get easier. The ledger does not work that way. A tax is a claim on income that already exists. It does not grow the supply of housing, food, energy, or labor. It rearranges who keeps the proceeds of production, and it changes how much production happens next.
Affordability is not a press release about who is being taxed. It is after-tax income divided by the prices of the things households actually buy. Raise the tax and the numerator falls. Raise the tax on the firms that make those things and the denominator often rises too. That is a worse ratio, not a better one.
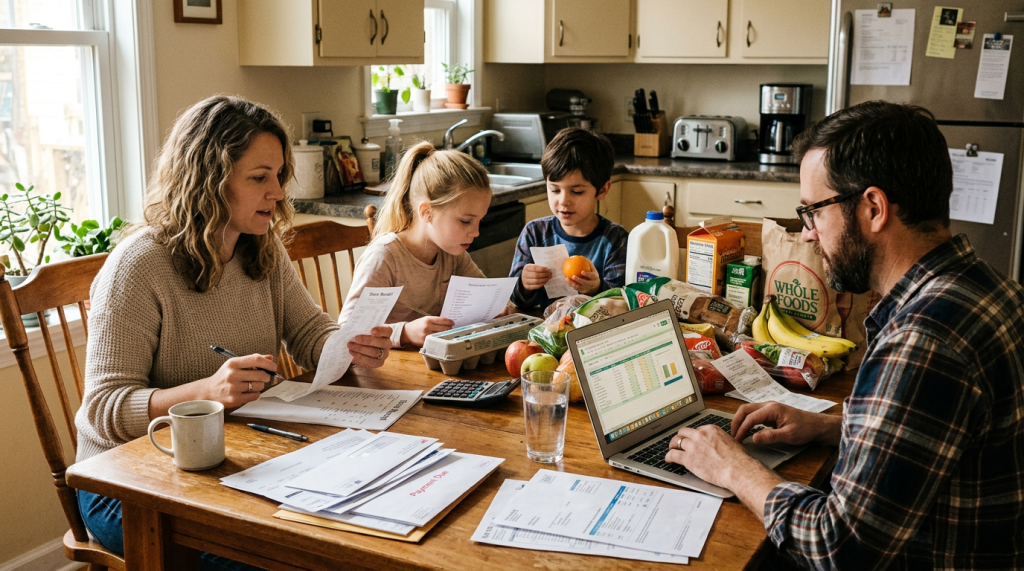
Families do not get a discount for paying more
An individual or family tax increase is a direct cut in take-home pay. Payroll and income taxes hit the wage before the grocery run. There is no mechanism in the tax code that marks down milk, rent, or a used car because the IRS took a larger share.
The macroeconomic record is blunt. Christina Romer and David Romer’s narrative study of postwar U.S. tax changes found that a tax increase equal to 1 percent of GDP reduced real output by about 3 percent over the following three years, largely because investment collapsed. Later work by Karel Mertens and Morten Ravn linked lower average personal income tax rates to higher employment and a quick rise in private investment — on the order of a few percent within a year of a 1-point rate cut. The mirror image is the policy now being sold as relief: higher rates, weaker hiring, less capital per worker.
Demand-siders sometimes answer that a personal tax hike can cool inflation by draining spending. A 2023 American Economic Association paper by James Cloyne, Joseba Martinez, Haroon Mumtaz, and Paolo Surico found that postwar U.S. personal income-tax increases did lower prices across many sectors, consistent with a demand channel. That is not a victory for affordability. Prices eased because households had less money to spend. Real purchasing power did not improve. You do not make a family richer by taking income away and then pointing at a slightly softer price index.Corporations do not pay taxes. People do.
A corporation is a legal form, not a taxpayer with a stomach. The corporate income tax is remitted by the firm and borne by some mix of workers, customers, and owners. In an open economy, capital can leave. Labor and local customers cannot, so they absorb a large share of the burden.
The evidence has moved away from the old classroom story that shareholders pay it all:
- A review of the incidence literature by the Tax Foundation finds that workers commonly bear half or more of the corporate tax, with many open-economy estimates at 70 percent or higher, because capital is mobile and labor is not.
- Baker, Sun, and Yannelis, linking retail prices to state corporate-tax changes, estimated that a 1-point corporate rate increase raised retail prices about 0.17 percent. Combined with wage evidence, they put the split near 31 percent on consumers, 38 percent on workers, and 31 percent on shareholders. Lower-priced goods — the ones poorer households buy — moved about twice as much.
- The Joint Committee on Taxation and the Congressional Budget Office already assign a meaningful share of the corporate tax to labor in their distributional tables. The debate is over how large that share is, not whether it is zero.
So a higher corporate rate is a tax on paychecks and a tax on the shelf. It is also a tax on retirement accounts, which own a large slice of U.S. equities. Calling that “taxing corporations instead of families” is an accounting fiction.
The inflation channel runs through supply, not slogans
Inflation is mostly a monetary phenomenon. Fiscal policy still matters at the margin, and corporate taxes hit the wrong margin.
The same Cloyne study that found personal tax hikes can dampen prices found the opposite for corporate tax hikes. Higher average corporate rates did not tame inflation. They were associated with persistently higher prices, especially for durable goods and capital equipment — exactly what you would expect if the tax raised the cost of investing in the machines that make goods cheaper over time. Personal tax hikes cooled inflation expectations. Corporate tax hikes mostly hit stock prices and supply.
That is the opposite of an affordability program. You cannot tax the cost of capital up and then act surprised when houses, cars, and appliances do not get cheaper.
The 2017 Tax Cuts and Jobs Act is the recent U.S. test in the other direction. The statutory corporate rate fell from 35 percent to 21 percent, with more generous expensing. A 2024 NBER survey of the evidence (Chodorow-Reich, Zidar, Zwick, and others) reports a loose consensus that tangible corporate investment rose about 11 percent, with firms facing larger cuts investing more. Brookings has argued the aggregate investment gain was partly a reallocation away from pass-through firms. Even on that more skeptical reading, the firms that actually received the rate cut invested more. Reversing the cut does not conjure a free lunch. It raises the hurdle rate on the next factory, warehouse, and software system.

Unemployment follows the capital stock
Jobs are not a gift of the tax schedule. They are a bid by firms for labor, and that bid depends on how much capital sits beside the worker. Tax labor income more heavily and some hours disappear at the margin — second earners, overtime, late-career work. Tax the return on capital more heavily and the plant does not get built, the shift does not get added, and the wage premium that comes from better tools never arrives.
Tax Foundation scoring of recent business-tax increase proposals — book minimum taxes, broader limits on compensation deductions, higher buyback taxes, tighter state-and-local deduction rules for corporations — routinely shows small but real losses in hours worked, capital stock, and long-run wages. The Inflation Reduction Act’s business-tax pieces alone were estimated to cut long-run GDP about 0.2 percent and eliminate roughly 29,000 full-time-equivalent jobs. Those are not catastrophic numbers. They are also not an affordability dividend. They are fewer tools per worker and slightly lower pay, enacted in the name of relief.
The closed gate is the honest picture of a tax on investment. A “Help Wanted” sign on a locked fence is what happens when the after-tax return no longer clears the cost of hiring.
What actually makes life cheaper
Prices fall when more is produced per hour, not when Congress announces a new bracket. The postwar episodes that improved American living standards — the 1960s Kennedy cuts, the 1980s Reagan reforms, the 2017 corporate-rate cut and expensing — worked by raising the return to work and capital. They were not free. They traded static revenue for a larger base. The alternative, repeated in the late 1960s and 1970s and again whenever rates and regulatory costs piled up together, was stagflation: weak real growth and prices that would not behave.
A conservative affordability agenda is therefore almost the inverse of a tax-increase agenda:
- Keep marginal rates on work and investment low enough that the next hour and the next machine are worth doing.
- Expense capital quickly so the tax code does not punish the investments that raise productivity.
- Stop treating corporate taxation as a moral category. It is a tax on workers, shoppers, and savers, and it is one of the least efficient ways to fund the government.
- Restrain the spending that makes tax hikes look inevitable. Deficits financed by money creation are an inflation tax. Deficits financed by future tax hikes are a growth tax. Households pay both.

There is no version of this in which a heavier levy on families and firms produces cheaper groceries and fuller payrolls. The tax can move money into the Treasury. It cannot move goods onto shelves. Affordability is a supply story. Tax hikes are a supply cut.